AI and chip stocks are getting crushed. Nvidia, AMD, Qualcomm, Micron, Intel, and other semiconductor and AI infrastructure names are falling sharply (some 5–13%+). Investors are worried that the massive AI data-center build-out could slow because of high borrowing costs and potential new regulations or pauses under a Democratic-controlled Congress. This follows a longer period of concern about whether the huge AI spending will actually pay off.
Mag 7 falter
Further, Amazon and Intel earnings revived concerns over massive AI capital spending and weak free cash flow. Strong quarters are not enough in the era of heavy AI capital expenditures. Investors want proof the spending pays off. Amazon’s net sales rose 12% to $201.9 billion and AWS jumped 39%, the cloud unit’s fastest growth in nearly five years, with operating margin at a record 13.9%. Yet the stock still sold off after the company maintained roughly $220 billion in expected capital expenditures. Intel grew revenue nearly 21% and data center and AI sales soared nearly 78%, its strongest data center growth in 15 years, but the stock collapsed on a softer fourth-quarter outlook and lower expected margins.
The same treatment hit Alphabet a day earlier. Revenue grew nearly 25% to $127.57 billion and free cash flow turned negative after heavy capex, producing the company’s largest post-earnings gap down since it went public. Caterpillar likewise gapped lower sharply despite solid sales growth and a record backlog simply because it reiterated its prior outlook. Four examples in a row of just how high the earnings bar has climbed. Investors have already paid for the AI build out, so they are selling anything that suggests it could slow or cost more than expected.
On global liquidity
In addition, the Global Liquidity cycle appears to be rolling over, yet this is no conventional monetary squeeze. With debt burdens high and little appetite for austerity, policymakers avoid indiscriminate tightening. Liquidity is instead absorbed by the real economy through fiscal expansion, resilient nominal growth, and the AI-driven capex boom, drawing funding away from financial markets toward productive investment and working capital.
The Fed’s priorities have shifted from aggressively restricting conditions to fight inflation toward preserving Treasury-market stability and balance-sheet capacity to intermediate rising government debt. This is not traditional yield curve control. Policymakers are keeping the core funding and collateral market liquid and orderly even as AI capex adds another major call on capital. Monetary restraint has moved from an exogenous central bank squeeze to an endogenous competition for funds. Wall Street is increasingly competing with Main Street for liquidity, which can moderate Global Liquidity without an overt Fed tightening cycle.
Treasury adjusts the composition of issuance in what amounts to Treasury QE. The Fed maintains ample reserves and market backstops to support Treasury financing, while the real economy absorbs liquidity through spending, capex, and working-capital demand. Policy can therefore support Treasury-market liquidity while becoming less supportive of general asset prices. That is the essence of the shift from Fed QE to Treasury QE.
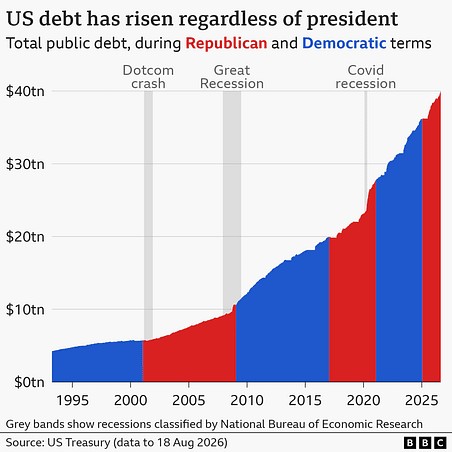
Yet the post-2008 pattern holds. The Fed has repeatedly stepped in during stress, and US public debt has continued to rise under both Republican and Democratic administrations. The structural expansion of government liabilities, combined with the residual Fed put, continues to limit the depth and duration of broader liquidity contractions even as near-term competition for capital intensifies.
That said, the AI spending narrative remains a concern and can keep slamming tech leadership until evidence of monetization improves. The election outcome was a negative for pure AI/data-center exposure.