Fed hiked 25 bp. Priced. The old textbook — rates up, averages down — is a relic. Also first rate hike is typically bullish over time because it suggests strength in the economy. That said, this is a market of leading stocks. The names that drag NDX and SPX have been numerous.
But liquidity remains the umbrella. Dollar, TGA, reserve growth. A quarter-point does not drain the pool given QE in all its forms.
Every AI chip that ships gets lit. VanEck said it straight: nothing sits in a warehouse. They cannot build them fast enough. Dot-com left dark fiber — cable poured before anyone had a use. This cycle starts with a population that is already digital. The genie is out.
Overbuild is possible. Model efficiency can catch compute. That is the bear case. Near term it is hard to see. A data center takes two to three years to stand up. Demand usually cools before the last hall is live. That lag is a governor. It keeps silicon scarce enough that construction does not sprint miles ahead of use.
Hyperscalers are not chasing a quarter. Amazon, Alphabet, Meta have five-to-ten-year funding cycles. This is a different animal from a product launch tied to next earnings.
Indeed, the stack reinforces itself. Nvidia designs. TSMC fabs. ASML sells the tools. Critics scream circular finance. The other side is that each layer needs the others alive. That is how a complex organism stays in motion. Washington can slow it, but China competition makes a hard clamp less likely.
SMH +78% in twelve months. More than 4× the S&P since ChatGPT. Stay with constructive price/volume in the names that are actually outperforming. The old playbook was “capex equals bust" but this tape is still a shortage.
Now the chart you see that argues with the above.
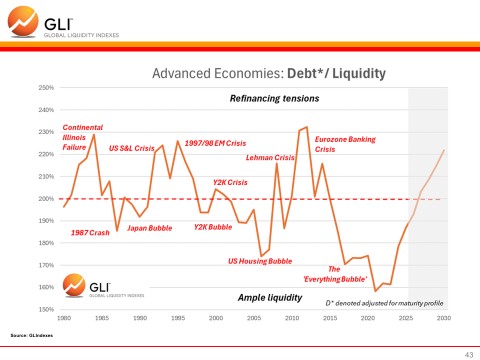 The dashed level around 200% is the “normal” band. Above it, refinancing gets tight and crises show up. Below it, cash sloshes and bubbles get built. The Everything Bubble was not a high-stress reading. It was the deep dip after 2020, down near 140%. Too much liquidity versus debt.
The early-2010s spike above 200% after Lehman and the euro mess was the stress side. Then the line fell for years as QE and cheap money flooded the system. That falling line is why a 3x tech vehicle like TECL could grind. Pullbacks. Resistance. The trend still won because the ratio was heading the wrong way for bears: down, into excess cash.
So the bubble was not “alive” because the ratio sat stuck above 200%. It was built while the ratio was falling. What is alive now is the hangover. Debt stock is still huge. The refinance wall was delayed, not cancelled. The line has already turned up off that trough.
Debt continues to accelerate. Liquidity is cyclical. A strong real economy can pull cash out of the financial system. Liquidity may be under pressure at times, but old debt still has to roll. Unless official print matches that debt, the ratio climbs toward 2.0–2.2. Historically that path favors cash first, then stress, then a central bank rescue.
AI leaders already took the deep correction. That is the washout the crowd wants to label “the top.” In O’Neil terms a major top is climax volume, wide-and-loose breakdown through the 50-day, then the 200-day, with the leadership group failing as a set. A sharp reset inside an ongoing theme — especially when the survivors reclaim moving averages on constructive volume — is more often a mid-cycle shakeout than the end of the move. The hike week told the same story: NDX and SPX flat, leaders that refused to break after “sell the news.” Institutions still have to own the names that print 20–30% earnings. This swamps 25 bp hikes.
Also to remember that data-center build is not 2006 mortgage product. Different funding. Lower first-order rate sensitivity. Versus 2022 with rates rising faster than ever, this tape is not restricted. But also keep in mind a 22× market that needs the story to stay perfect is not a free ride. Keep that distinction.
A falling liquidity-to-debt ratio is rocket fuel for leveraged tech. A rising ratio is thinner fuel so the leftover-liquidity bid gets pickier. That is why you stay with constructive price/volume in the names that actually continued to grow through the correction.
The only way you get the easy 2020-style melt up is if liquidity outruns debt again and the line rolls over. That is a policy decision. Until then the job is the same. Major tech centric averages should continue to rise while those AI leaders support the repair and volume stays constructive. The correction was unlikely the major top. The hangover chart is the risk. The leaders are still the signal.