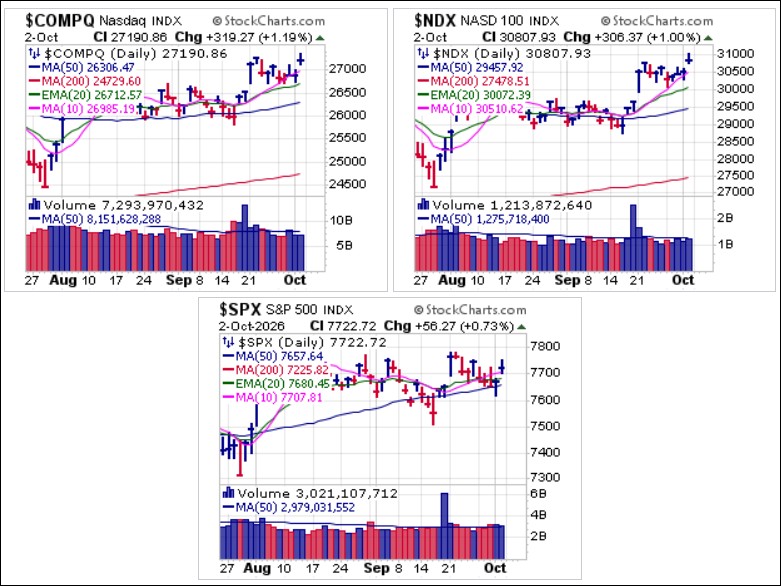
Nonfarm payrolls rose by 29,000, well below the 90,000 new jobs economists had expected. Nonfarm private payrolls rolls by 50,000 vs. estimates of 100,000. The unemployment rate rose to 4.2% (7.1 million unemployed), from 4.1% in August. It has stayed in a narrow 4.1%–4.3% range since March. Jobs numbers reported in July and August were revised down by a combined 60,000. July went from +21,000 into the red at −10,000, and August was revised from +162,000 to +133,000.
While stocks at the margin rallied on the news, it was not enough to reverse the trend in long Treasury Yields. Both the 10-Year Treasury Yield ($TNX) and 30-Year Treasury Yield ($TYX) ended the day and the week near their prior 19-year highs.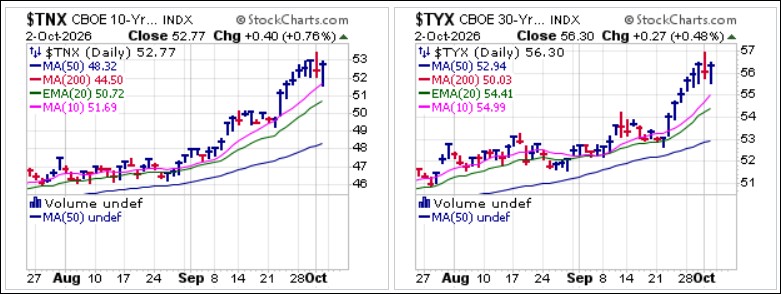
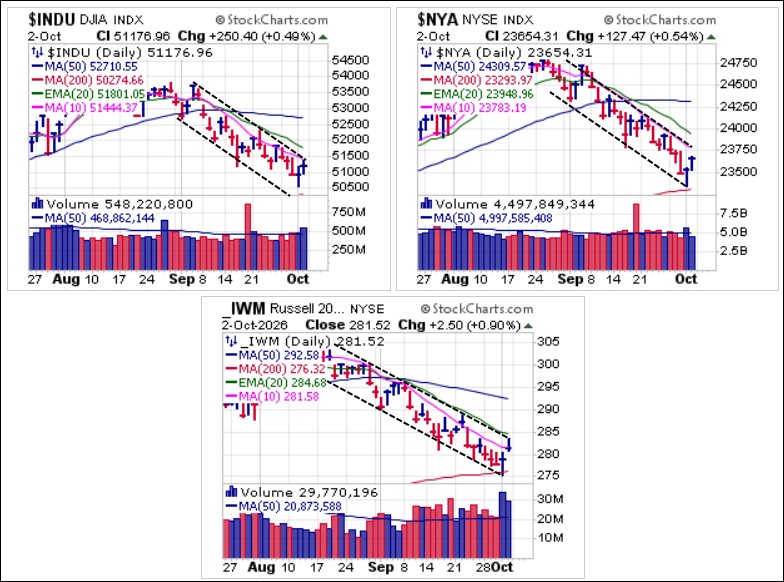
The non-tech centric areas of the market including the Dow, NYSE Composite and small-cap Russell 2000 all bounced over the past two days to avoid ending the week at fresh lows. All three indexes remain within well-defined downtrend channels with the NYSE Composite bouncing off 200-dma support on Friday. Not much to see here as the rest of the market, mostly the economically-sensitive and consumer-oriented sectors, stages what is so far a two-day oversold bounce.
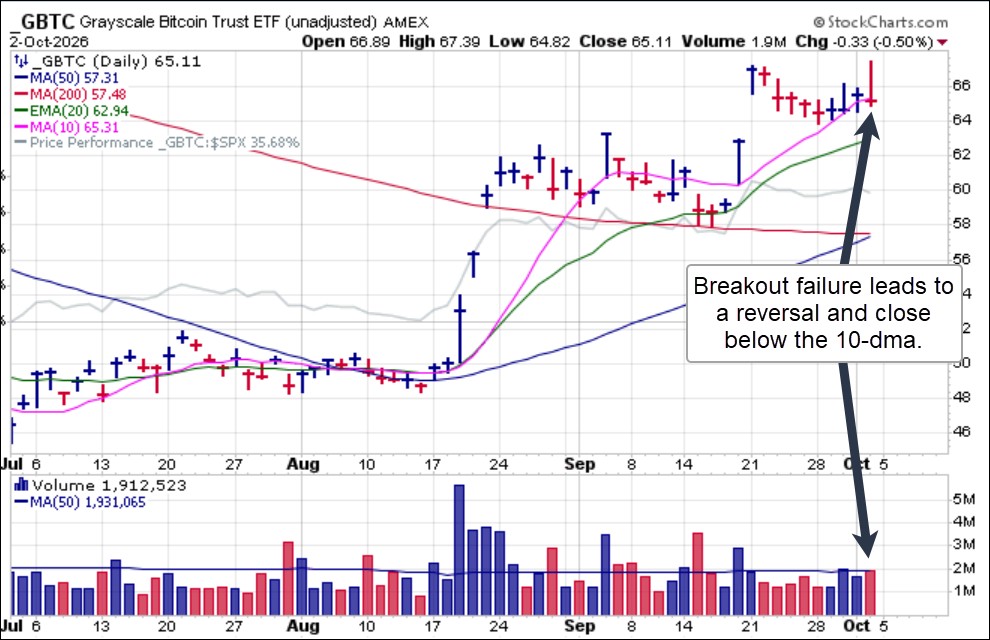
 Bitcoin ($BTCUSD) reversed badly on Friday, sending the Grayscale Bitcoin Trust (GBTC) back through its 10-dma after failing on the breakout attempt earlier in the day. A test of the 20-dema may be in the cards, but for now GBTC remains within a short nine-day flag formation.
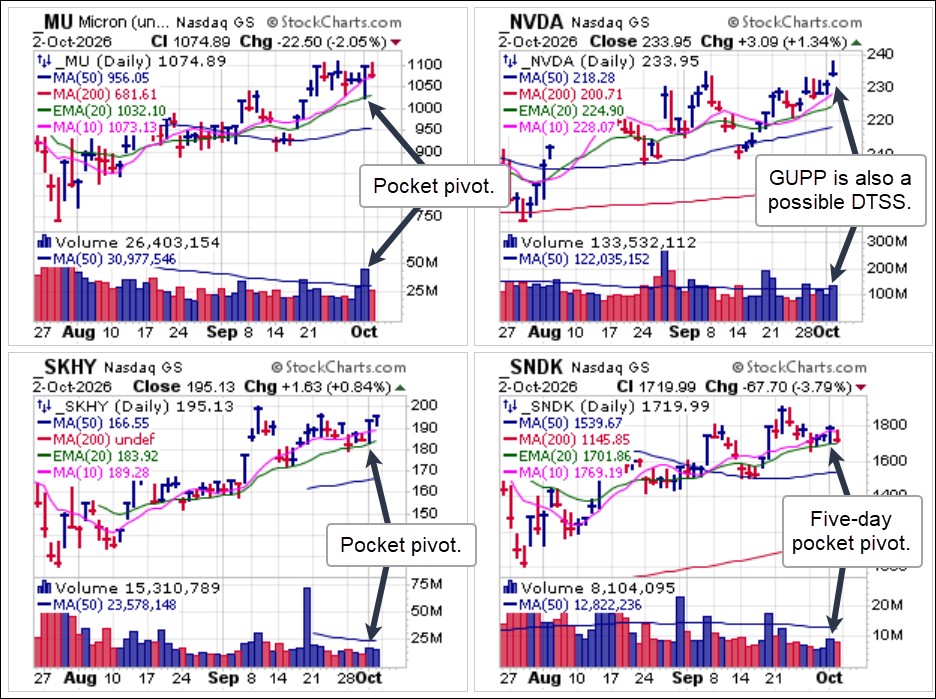
 Other names we reported on Thursday as the market turned off the lows included Micron Technology (MU) and SanDisk (SNDK) which were posting pocket pivots at that time. Only MU followed through with a bona fide pocket pivot. Both stocks were likely soft as a result of a report from Nikkei that Japanese rival Toshiba plans to double its fiscal 2027 production capacity for drives used in AI data centers which sent drive makers Seagate Technology (STX) and Western Digital Corp. (WDC) plunging -10.21% and -10.22% on the day, respectively.
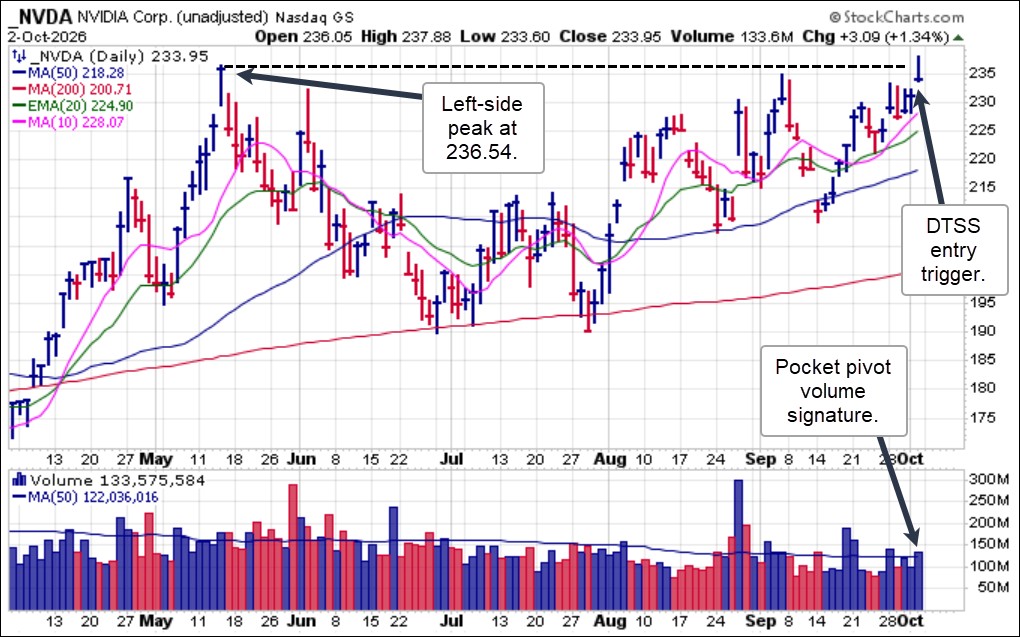
SK hynix (SKHY) also posted a pocket pivot at the 20-dema although early in the day on Thursday it looked to be posting a VDU pullback to the line instead, but things changed by the close. Leading AI semiconductor Nvidia (NVDA) gapped higher on Friday morning, which we reported on, but volume faded as the stock stalled and posted a gap-up pocket pivot (GUPP) and a double-top short-sale entry trigger on the same day.
 We get a better idea of the action in NVDA by looking at a six-month daily chart. Here we can see the clear reversal at the 236.54 left-side peak of mid-May. NVDA's early BGU faded by the close as volume declined, but still qualified as a stalling gap-up pocket pivot (GUPP). It remains to be seen which set-up will hold sway next week, but what started out as a potentially powerful BGU early in the morning Friday and then faded badly into the close is likely not the most bullish action you would want to see.
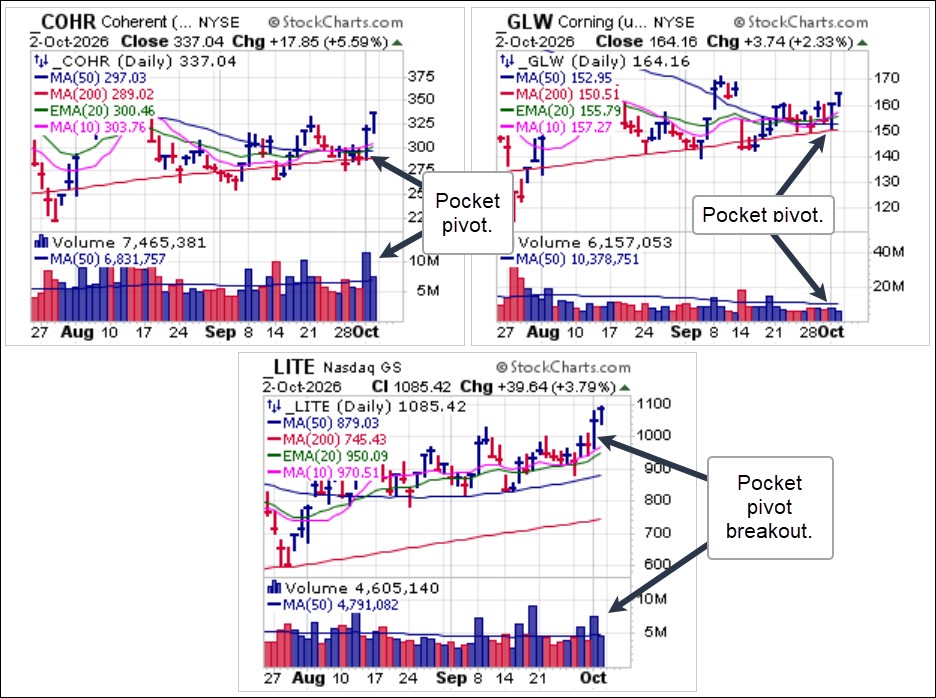
 Coherent (COHR), Corning (GLW) and Lumentum Holdings (LITE) were also reported as pocket pivots on Thursday and all three continued higher on Friday. They are now extended and out of buying range.
 Despite the weak jobs report on Friday, Treasury Yields rallied and stocks were tentative on what started out as a big opening rally but faded and lost momentum as the day wore on. Still a difficult environment where sustained progress is difficult.
The Market Direction Model (MDM) remains on a BUY signal.