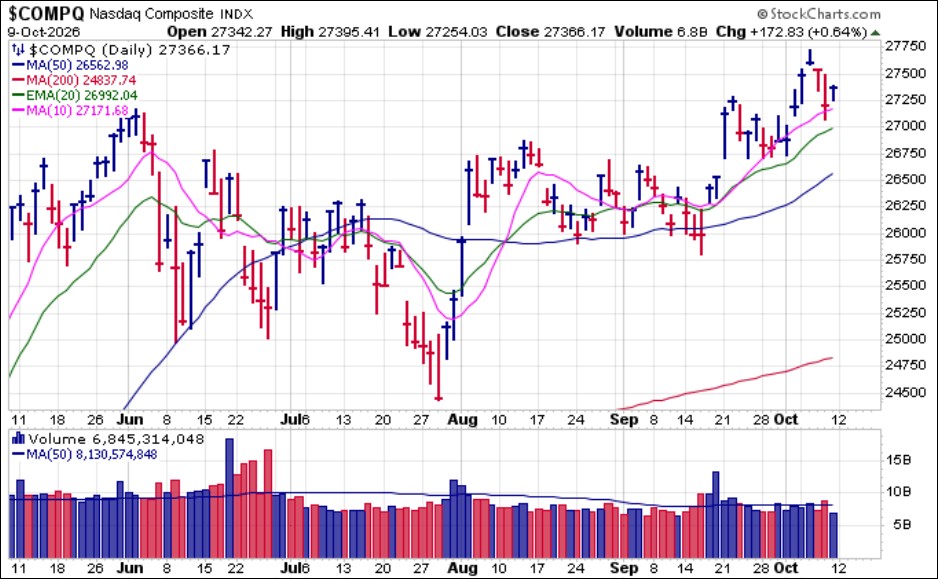
Korean chip maker Samsung missed on earnings Wednesday night in the Korean markets which put the kibosh on the new all-time highs posted by the
NASDAQ Composite and
NASDAQ 100 on Tuesday. Then, on Thursday, the
Financial Times reported that OpenAI had reported to investors that its annualized revenue was approaching about $50 billion at the end of September. That is roughly $20 billion below the roughly $68–70 billion figure circulating among the rumor mills late last month. That sent the market down again before recovering off 10-dma support on Friday after it was revealed that the OpenAI revenue miss was an accounting issue as the original $68-70 billion number included revenues to OpenAI's partners and the $50 million reported was OpenAI's share. For now, the NASDAQ Indexes and the
S&P 500 remain above 10-dma support after selling off their mid-week highs on Wednesday and Thursday.
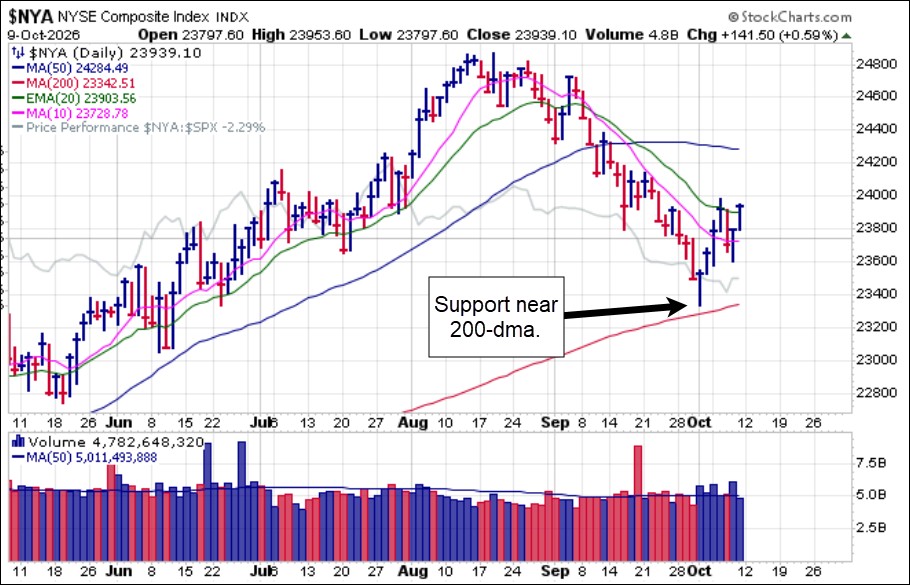
The
Everything Else Indexes, however, have continued to recover off their lows of rallied as the
Dow and
NYSE Composite turned positive on Thursday. The NYSE Composite, which well-represents stocks that are not tech-related is attempting to breakout of its downtrend channel after clearing the 20-dema on Friday. That is the index's first close above the 20-dema in over a month.
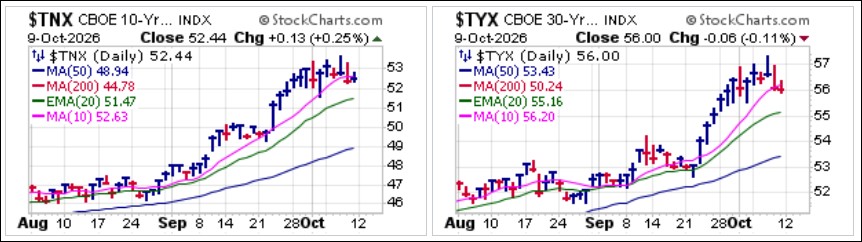
The
10-Year Treasury Yield ($TNX) and
30-Year Treasury Yield ($TNX) ended the week near their highs, despite the Treasury Department stepping in on Thursday to purchase $6 billion worth of bonds on the same day that it was auctioning off $22 billion in 30-Year Bonds.
Despite the rally in the tech centric indexes on Friday, a number of big-stock AI-related semiconductors that we reported on earlier in the week and last week continued lower.
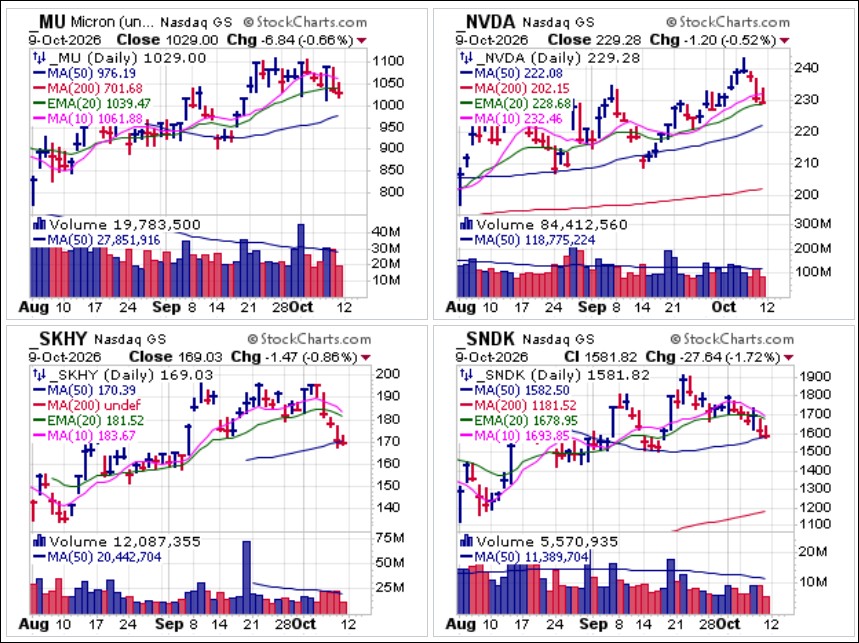
Micron Technology (MU) closed below 20-dema support on Friday which is technically a short-sale entry using the 20-day as a covering guide.
Nvidia (NVDA) posted a double-top short-sale (DTSS) entry at the 236.54 left-side peak of its current base and then on Friday reversed at 10-dma resistance. It ended the day just above 20-dema support which, if broken, would trigger another short-sale entry at that point.
SK hynix (SKHY) and
SanDisk (SNDK) closed Friday just below 50-dma support after triggering short entries at the 20-dema earlier in the week. These new breaks below 50-dma support could be treated as secondary short entries using the 50-day lines as covering guide. Overall, however, the action speaks to weakness in semiconductors despite the up day in the NASDAQ Indexes and the de-bunking of Thursday's OpenAI news.
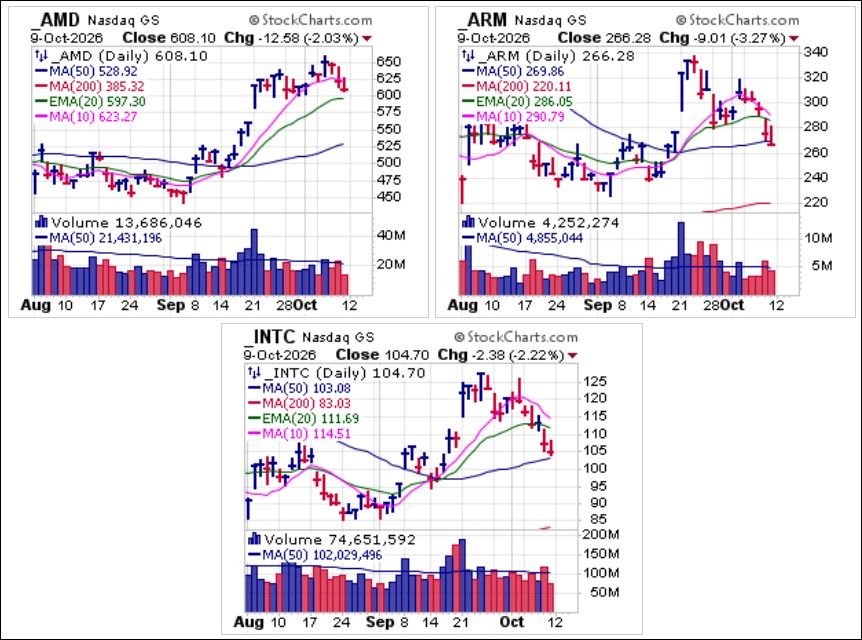
Semiconductor CPU makers, which caught fire back in September when
Meta Platforms (META) announced the strong acceptance of its new
Mime Agentic AI iPhone app that runs on CPU power, have all started to come unraveled.
Advanced Micro Devices (AMD) busted 10-dma support on Thursday to trigger an aggressive short-sale entry at that point and now appears poised to test 20-dema support. Both
Arm Holdings (ARM) and
Intel (INTC) broke 10-dma and 20-dema support earlier in the week, triggering short-sale entries at the 20-day on Thursday before closing at lower lows on Friday. ARM also ended the week below 50-dma support where a third short-sale entry was triggered while INTC is now testing 50-dma support.
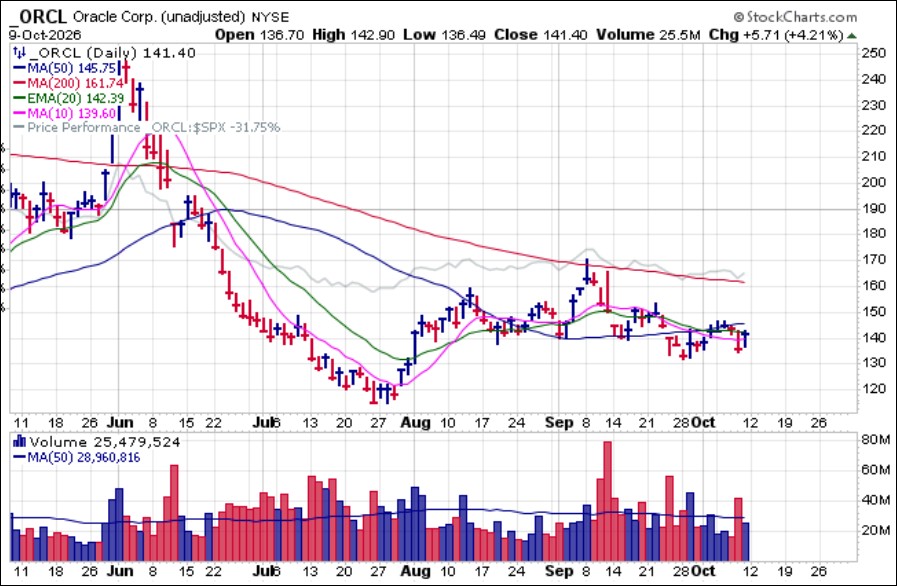
 Oracle Corp. (ORCL)
, a major AI infrastructure partner of OpenAI, mainly via the
Stargate Project and a large multi-year cloud capacity agreement, sold off on the Thursday news but rallied back up to moving average resistance on Friday. This potentially brings it back into short-sale range as close to the 50-day line as possible and then using the line as a tight covering guide.
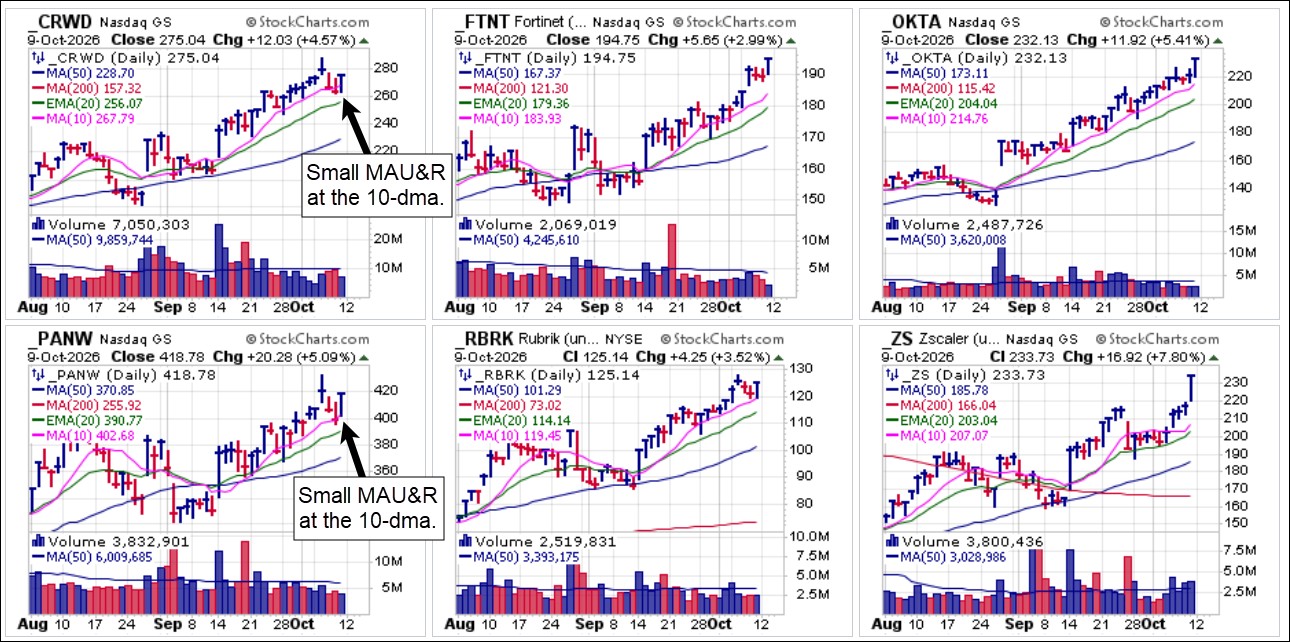
Cybersecurity names remain one significant bright spot among big-stock techs. On Friday, higher highs were seen in
Fortinet (FTNT),
Okta (OKTA) and
Rubrik (RBRK) while
CrowdStrike (CRWD) and
Palo Alto Networks (PANW) posted small MAU&Rs at their 10-day moving averages. Most of these names have followed the 10-dma for about seven weeks now, making the use of the Seven-Week Rule possible at the 10-day line.
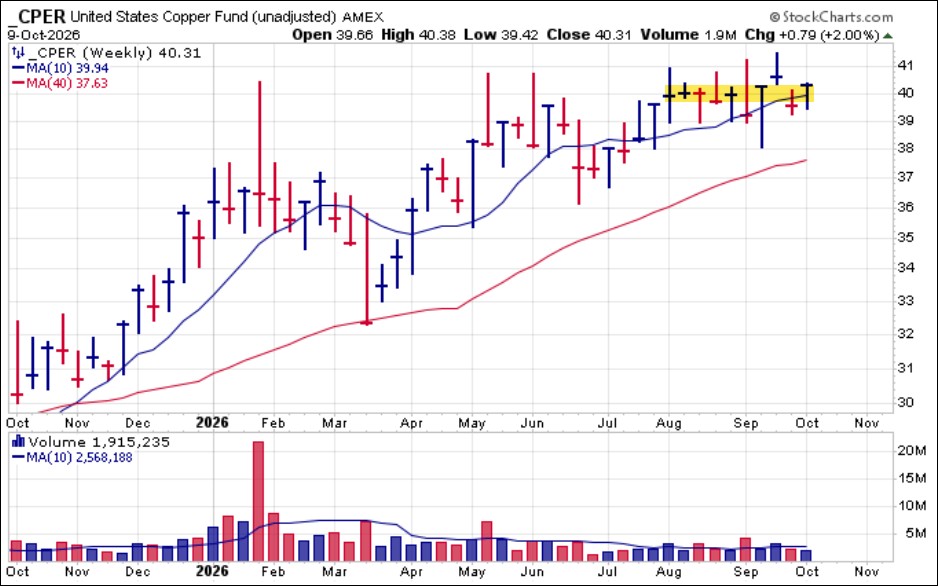
Copper remains volatile after breaking the 50-dma on Thursday before retaking the line on Friday. On the weekly chart of the
United States Copper Fund (CPER) it ended the week back above the 10-week moving average and again closed tight with prior weeks as highlighted on the chart. With or without AI, severe copper shortfalls remain a factor, and the resilience of copper prices amid an uncertain market environment remains firm, for now.
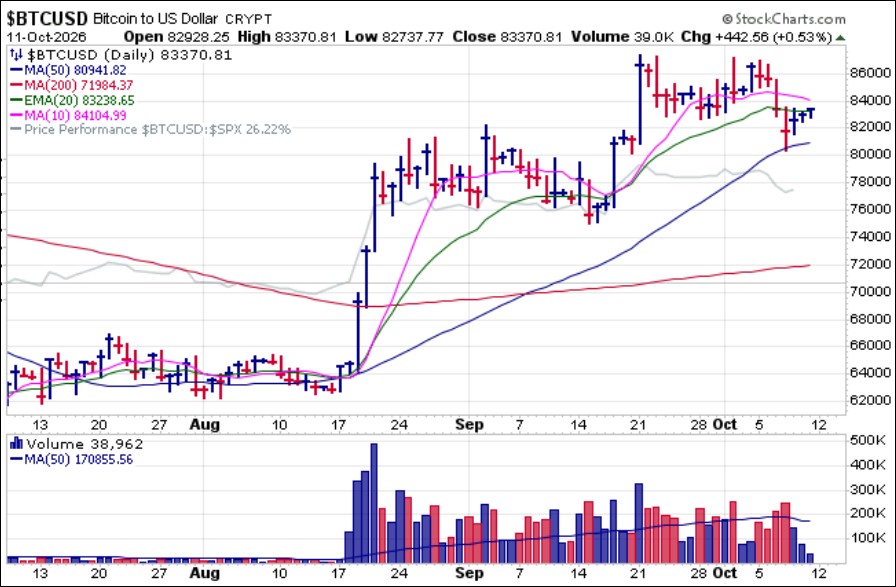
 Bitcoin ($BTCUSD)
failed from its current flag formation by busting the 10-dma earlier in the week. Over the weekend it is wedging back above the 20-dema on very weak buying volume such that any reversal back below the 20-dema could trigger a short-sale entry at that point. If it can hold 20-dema support then it could play out as an MAU&R at the line, so the situation here is quite fluid depending on how it plays out in the coming trading week.
The
Market Direction Model (MDM) remains on a BUY signal.
This information is provided by MoKa Investors, LLC DBA Virtue of Selfish Investing (VoSI) is issued solely for informational purposes and does not constitute an offer to sell or a solicitation of an offer to buy securities. Information contained herein is based on sources which we believe to be reliable but is not guaranteed by us as being accurate and does not purport to be a complete statement or summary of available data. VoSI reports are intended to alert VoSI members to technical developments in certain securities that may or may not be actionable, only, and are not intended as recommendations. Past performance is not a guarantee, nor is it necessarily indicative, of future results. Opinions expressed herein are statements of our judgment as of the publication date and are subject to change without notice. Entities including but not limited to VoSI, its members, officers, directors, employees, customers, agents, and affiliates may have a position, long or short, in the securities referred to herein, and/or other related securities, and may increase or decrease such position or take a contra position. Additional information is available upon written request. This publication is for clients of Virtue of Selfish Investing. Reproduction without written permission is strictly prohibited and will be prosecuted to the full extent of the law. ©2026 MoKa Investors, LLC DBA Virtue of Selfish Investing. All rights reserved.