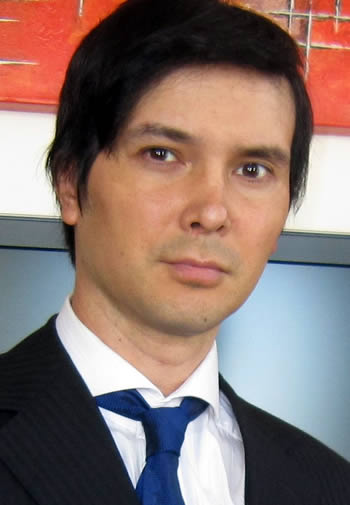
Markets continue to trade sloppily. While the
NASDAQ Composite and
S&P 500 were able to clear 50-dma resistance on Thursday, the broader market continues to languish. Big-stock techs have on balance, been more buoyant lately, perhaps due to last week's Goldman Sachs Technology conference. On Friday, triple-witching options expiration (OpEx) sent volume spiking on both exchanges, creating a very bullish look to the two charts below.
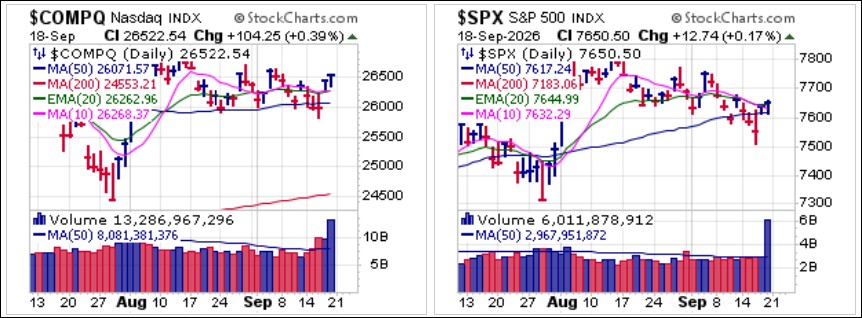
This is also seen through a comparison of the NASDAQ 100 and S&P 500 to their equal-weighted versions. Outside of the higher-weighted tech-centric areas of these indexes, things are not so constructive, thus we remain cautious.
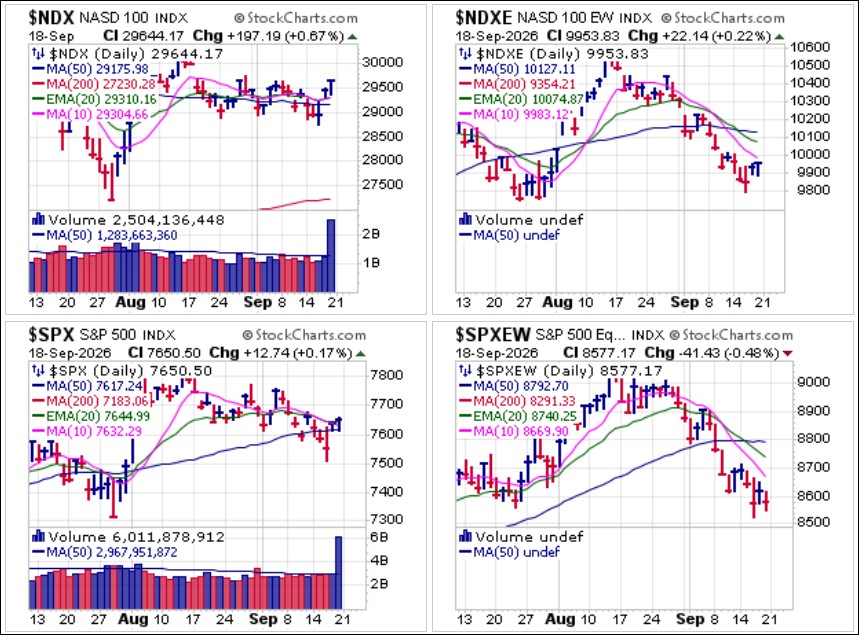
The divergence is also apparent in the action of the less tech-centric indexes, the
Dow,
NYSE Composite and small-cap
Russell 2000. All three remain in cascading trend channels and well below their 50-dmas as the 10-dma and 20-dema now cross to the downside.
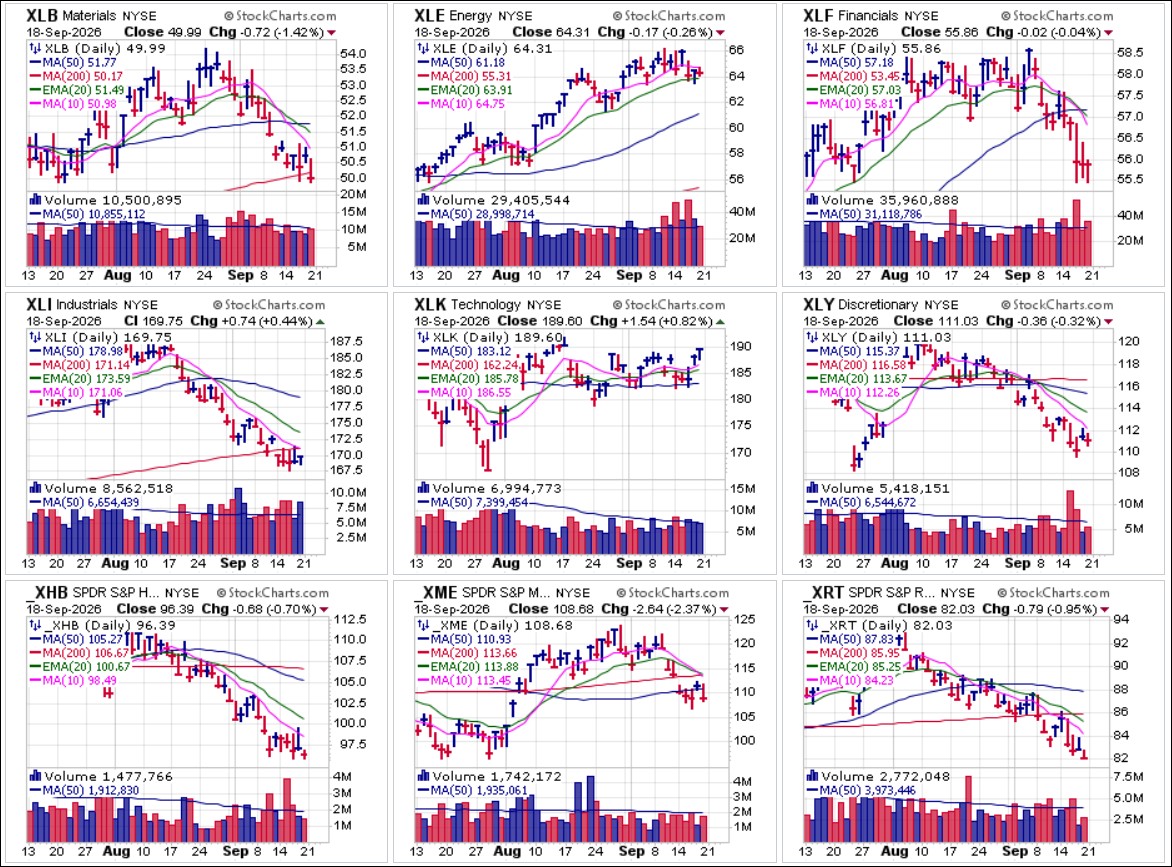
The divergence is also evident in the action of various sector ETFs. While the
Energy Select Sector SPDR (XLE) and
Technology Select Sector SPDR (XLK) ETFs continue to hold up, the rest of the market, consisting of economically-sensitive and consumer-oriented sectors, languishes, in particular, note the breakdown in the
Financial Select Sector SPDR (XLF) ETF as it slashed through 50-dma support this past week.
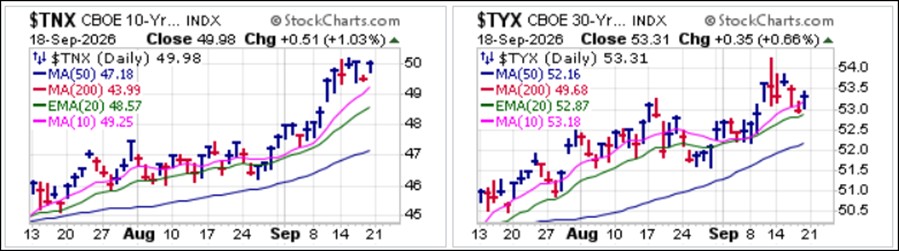
Treasury yields on the long end remain elevated as the
10-Year Treasury Yield ($TNX) hit a new 19-year high, trading intra-week as high as 5.04%. Mortgages and consumer and business credit are generally indexed to or influenced by the $TNX, so this has a direct economic impact. The $TNX remains well below its all-time high of 15.81% reached in 1982 during the era of Fed Chairman Paul Volcker who took an aggressive stance to quell the sharp inflation of the 1970's and early 1980's. Higher yields also put pressure on stocks, so we remain cautionary.
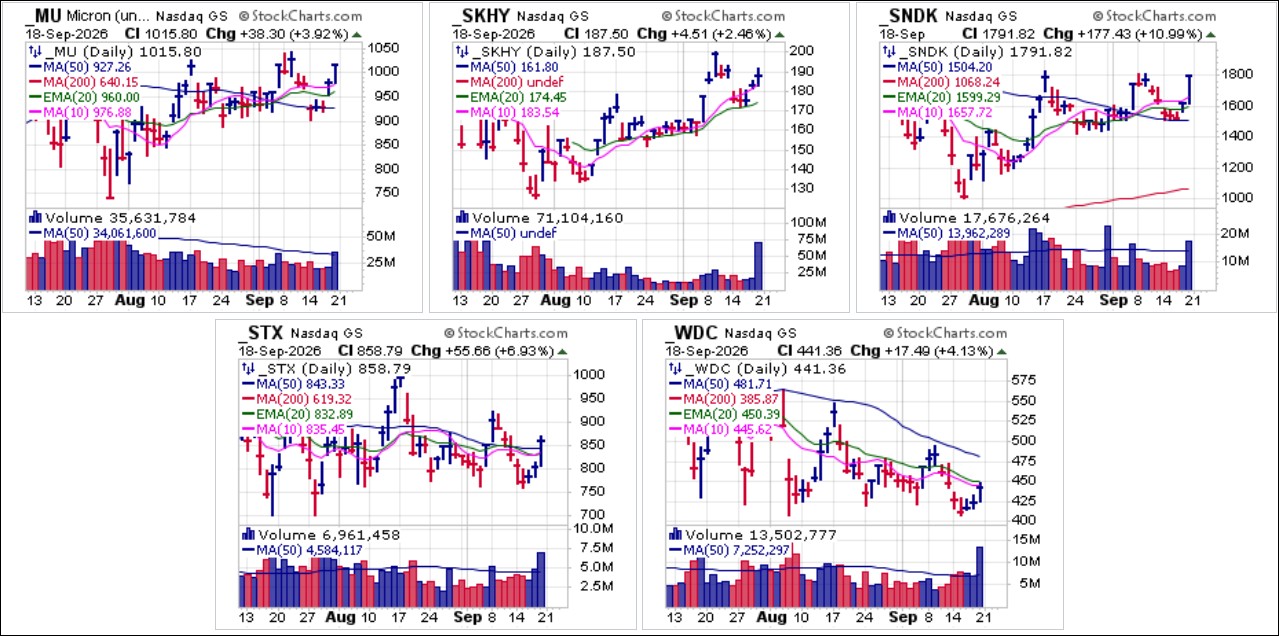
Heavy triple-witching quarter-end options expiration (OpEx) volume on Friday, perhaps in conjunction with re-weightings in the
NASDAQ 100 and
S&P 500, created some interesting pocket pivot moves in several big-stock techs, including memory makers shown below. Most were showing moderate volume but a late-day burst created the volume spikes you see below. These in turn created pocket pivots moves, mostly in extended positions and which are not not actionable on this basis. We are certainly open to seeing how these develop in the coming trading week or whether they eventually get throw into the one-day wonder trade pile.
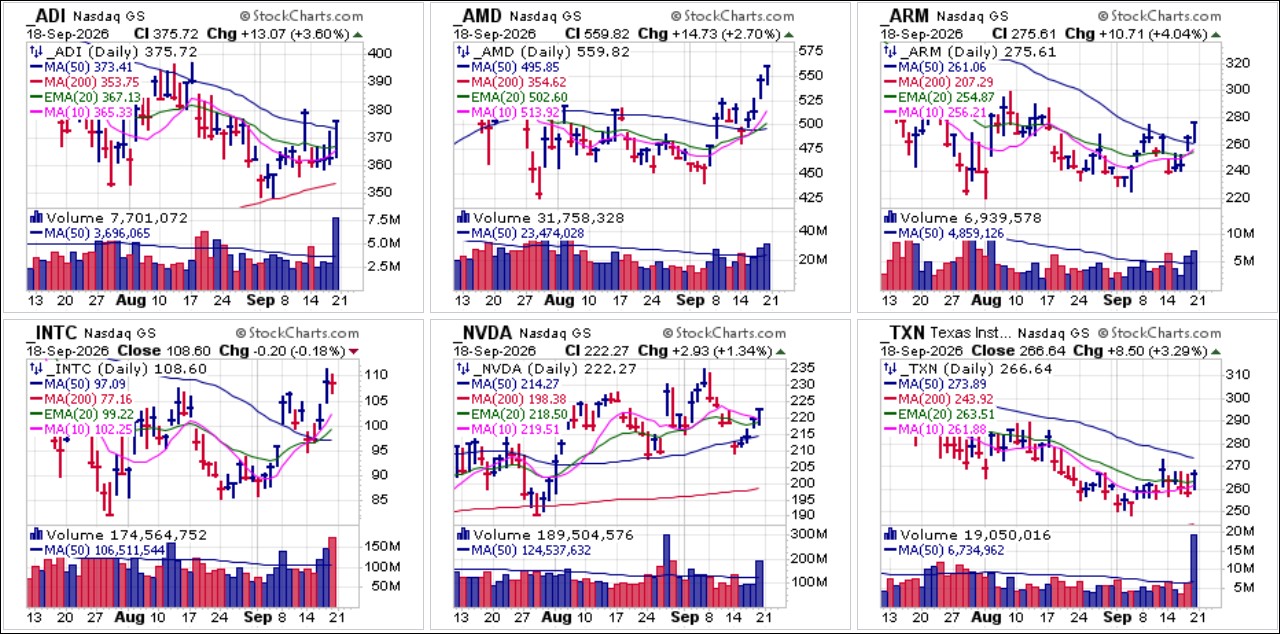
Other semiconductors that we track show similar pocket pivot volume signatures on Friday, but of these six, only
Analog Devices (ADI),
Nvidia (NVDA) and
Texas Instruments (TXN) are still within buying range using the nearest downside moving average as a selling guide. Again, however, we would watch to see how these develops to ensure they are not triple-witching OpEx induced one-day wonder moves.
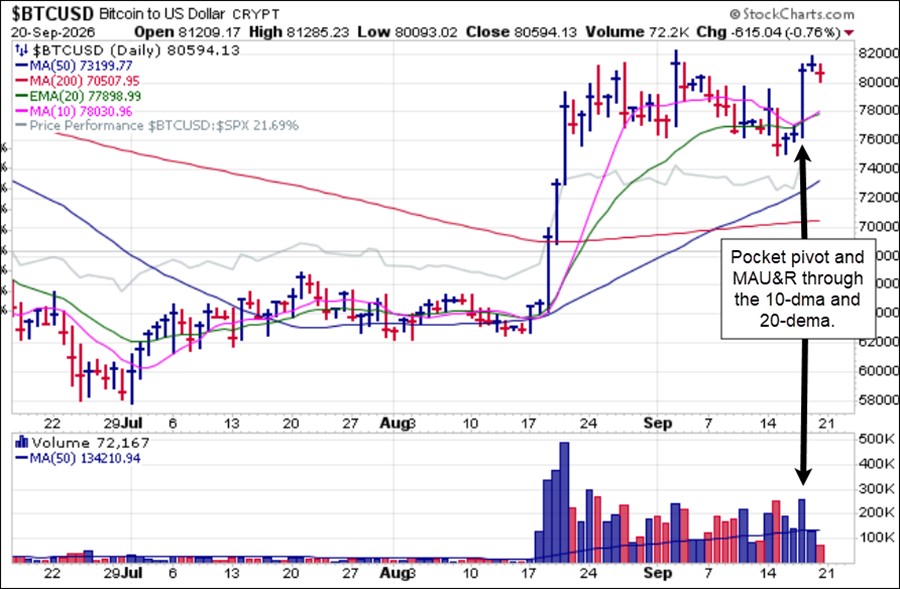
 Bitcoin ($BTCUSD)
posted a strong-volume pocket pivot on Friday as it now trades past the $81,000 level. It was initially actionable as an MAU&R at the 10-dma and 20-dema that morning and is now extended as it trades to higher highs over the weekend. Watch for constructive pullbacks to the rising 10-dma and 20-dema from here as a potentially lower-risk entries.
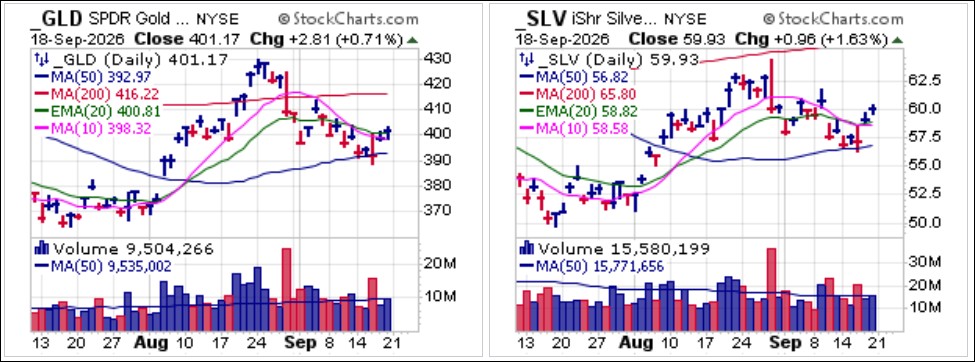
Gold and silver via the
SPDR Gold Trust (GLD) and the
iShares Silver Trust (SLV) both cleared 20-dema resistance at the end of the week to trigger MAU&R long entries. The GLD did so on Friday while the SLV did so on Thursday and continued higher on Friday.
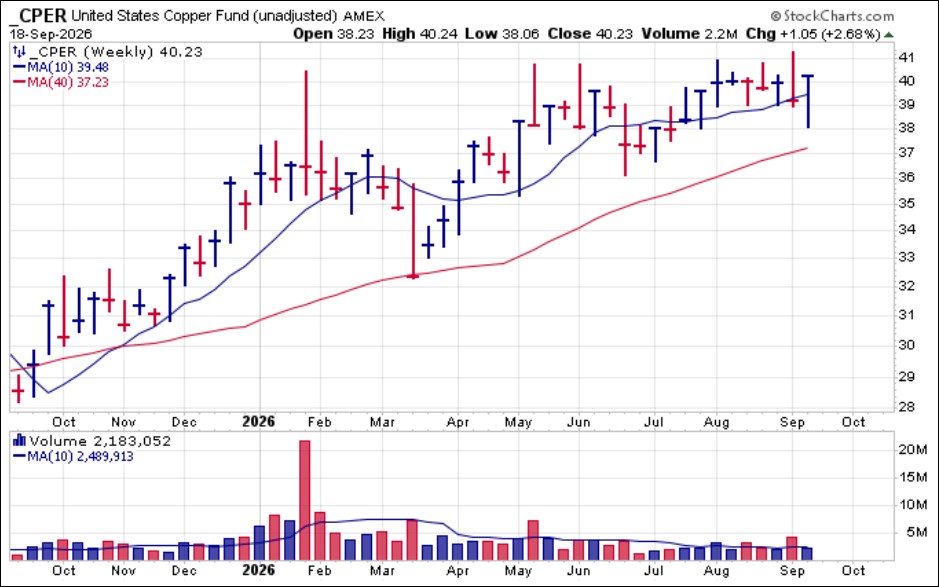
Copper has outperformed both gold and silver, despite a big spin-out over the past week as revealed by the weekly chart of the
United States Copper Fund (CPER). Surprisingly, even after a brutal start to the week, the CPER finished at an all-time weekly closing high as it posted tight weekly closes in five of the past six weeks.
The
Market Direction Model (MDM) switched to a
CASH/NEUTRAL signal on Monday, September 14, 2026.
This information is provided by MoKa Investors, LLC DBA Virtue of Selfish Investing (VoSI) is issued solely for informational purposes and does not constitute an offer to sell or a solicitation of an offer to buy securities. Information contained herein is based on sources which we believe to be reliable but is not guaranteed by us as being accurate and does not purport to be a complete statement or summary of available data. VoSI reports are intended to alert VoSI members to technical developments in certain securities that may or may not be actionable, only, and are not intended as recommendations. Past performance is not a guarantee, nor is it necessarily indicative, of future results. Opinions expressed herein are statements of our judgment as of the publication date and are subject to change without notice. Entities including but not limited to VoSI, its members, officers, directors, employees, customers, agents, and affiliates may have a position, long or short, in the securities referred to herein, and/or other related securities, and may increase or decrease such position or take a contra position. Additional information is available upon written request. This publication is for clients of Virtue of Selfish Investing. Reproduction without written permission is strictly prohibited and will be prosecuted to the full extent of the law. ©2026 MoKa Investors, LLC DBA Virtue of Selfish Investing. All rights reserved.