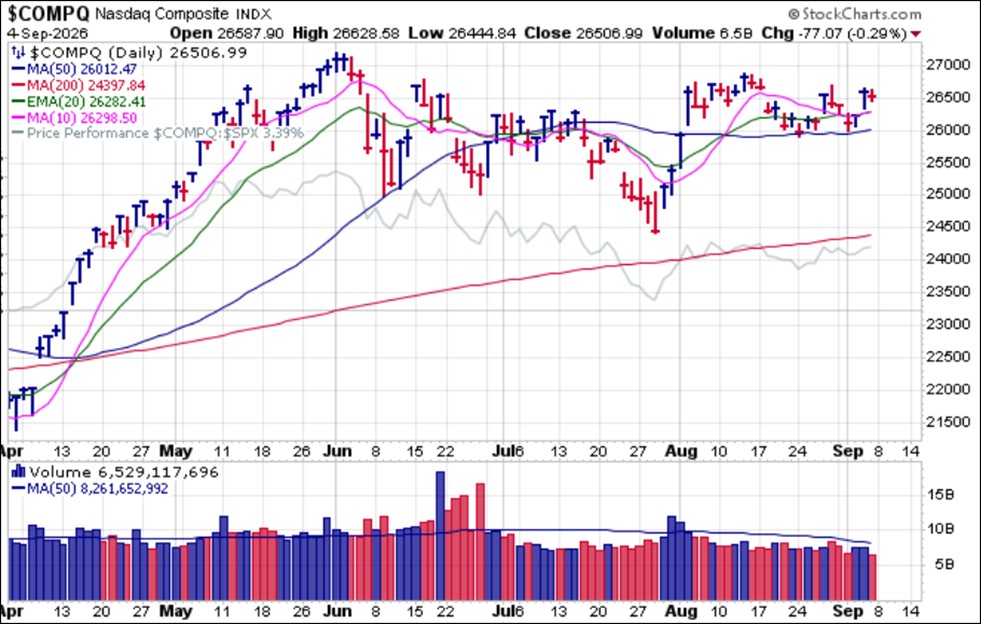
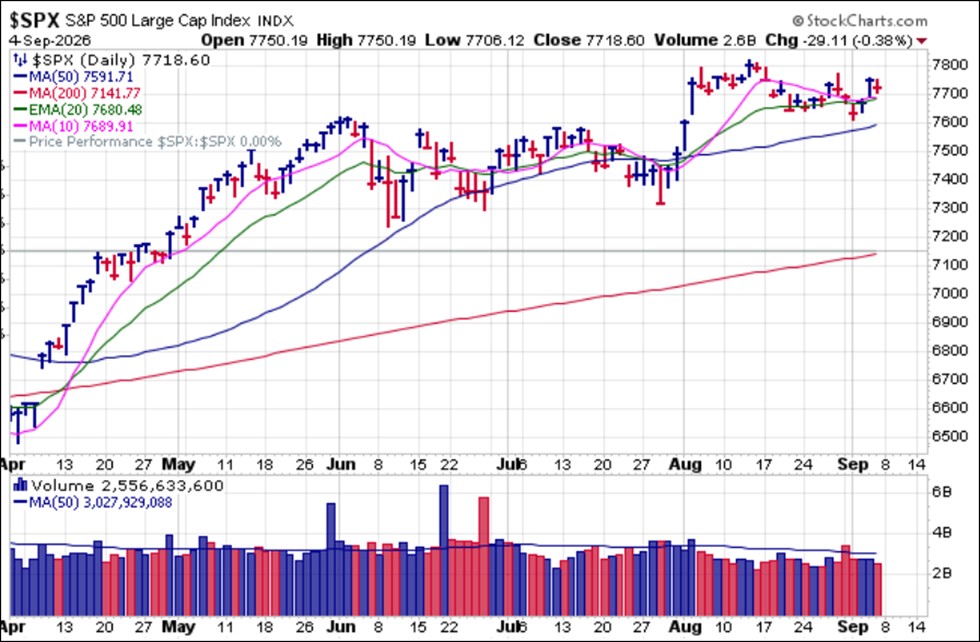
 While the NASDAQ Composite remains below its all-time highs, the S&P 500 set new highs in early August as it spent the month basing at higher levels. It also ended Friday slightly higher for the week. While the indexes are not trending strongly one way or the other, the overall action of an upside leg in early August followed by 4-5 weeks of sideways basing action cannot be considered bearish, and is in fact constructive.
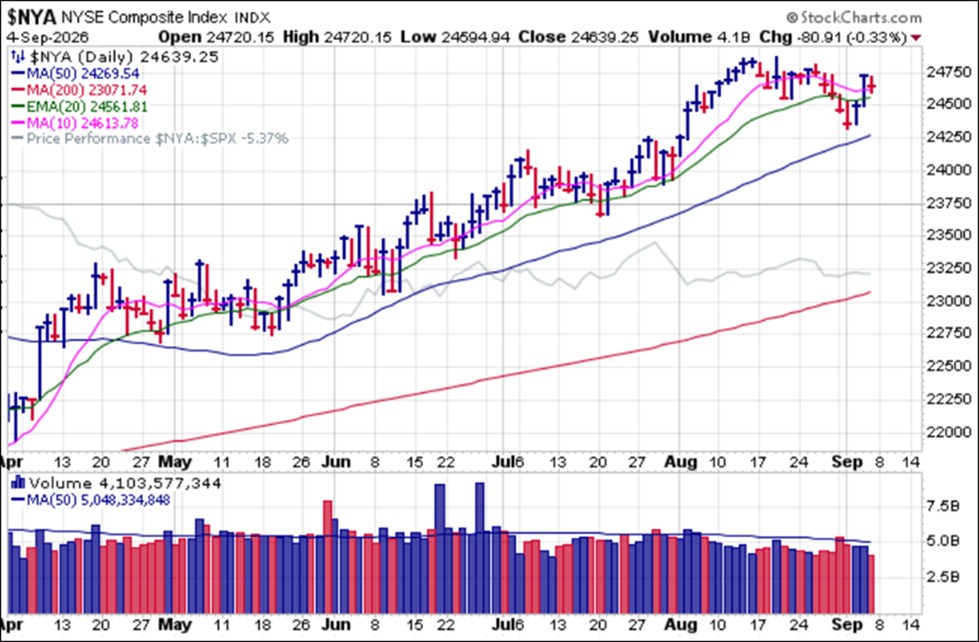
 The broader non-tech centric NYSE Composite also ended the week higher. It has been in a small three-week pullback since posting all-time highs in the second week of August and on Thursday regained both its 10-dma and 20-dema which it held by the end of the week. Again, as with the other tech-centric indexes, the action is mostly of a consolidating nature and cannot be seen as bearish.
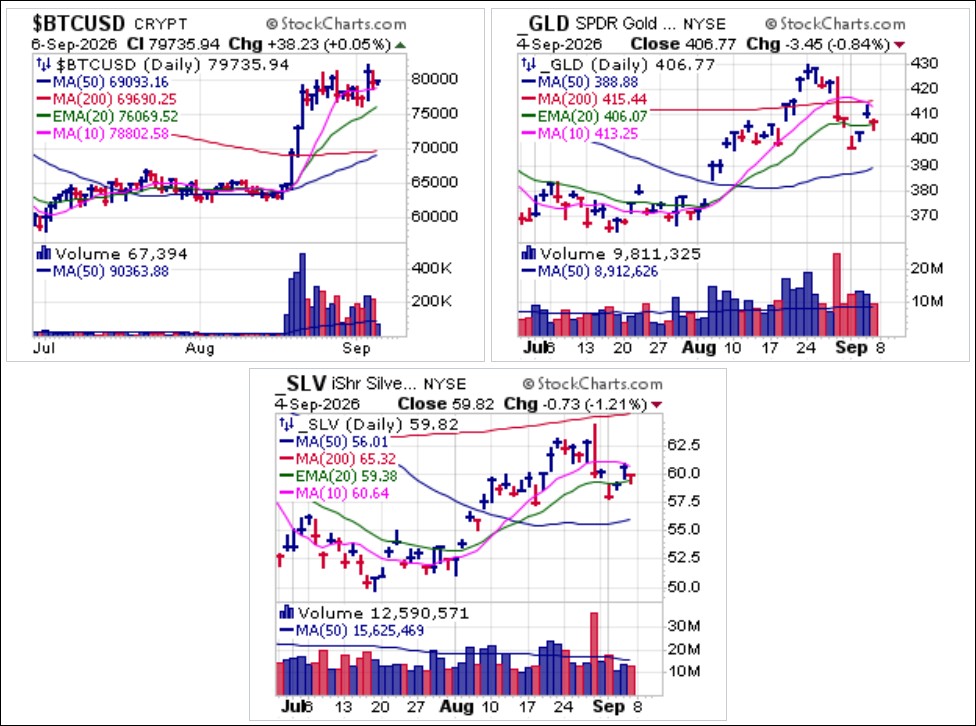
 Bitcoin ($BTCUSD) came back to life in August as its role as a potential alternative-currency in what has become the ABD trade (anything but the dollar. As a result, its correlation to gold is now at a six-year high. $BTCUSD and the SPDR Gold Trust (GLD), along with silver via the iShares Silver Trust (SLV) had torrid upside moves throughout August before correcting in response to Warsh's hawkish theatrics two Fridays ago. $BTCUSD remains in a two-week bull flag while gold and silver pullback and retrace their prior rallies in what appears to be normal fashion as both posted MAU&R long entries at their 20-dema on Friday.
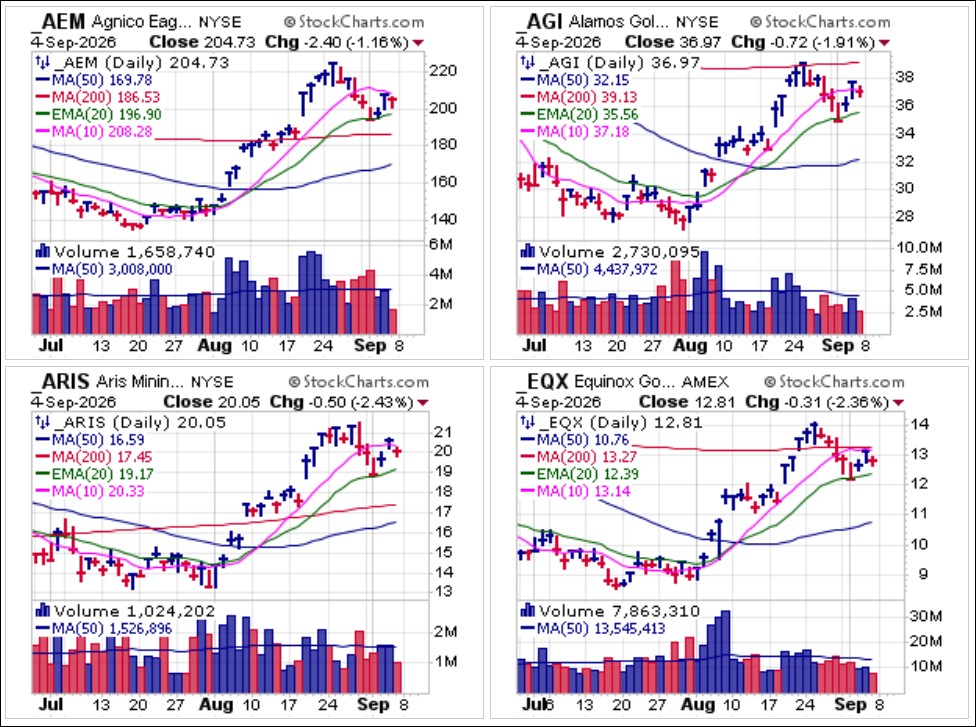
 Gold miners we reported on earlier in August as they launched on very sharp, steep upside runs also continue to consolidate in a similar manner as the GLD. The four shown below, Agnico-Eagle Mines (AEM), Alamos Gold (AGI), Aris Mining (ARIS) and Equinox Gold (EQX) all posted MAU&Rs at their 20-dema on Wednesday and are now holding tight as selling volume declines.
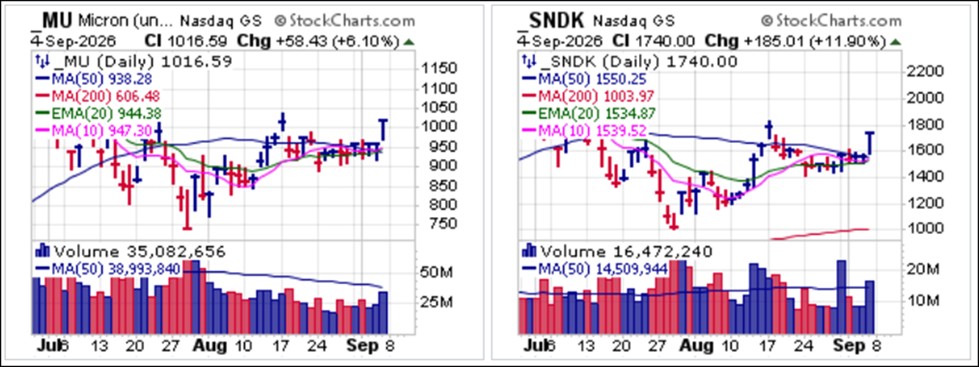
 On Friday we reported on pocket pivots in big-stock semiconductor memory/storage names Micron Technology (MU) and SanDisk (SNDK). Both stocks closed near the highs of their daily ranges as they approach the brief high of nearly three weeks ago. For now, these are extended and we would watch for pullbacks closer to the 50-dma as potential entries, assuming these do not play out as one-day wonder trades.
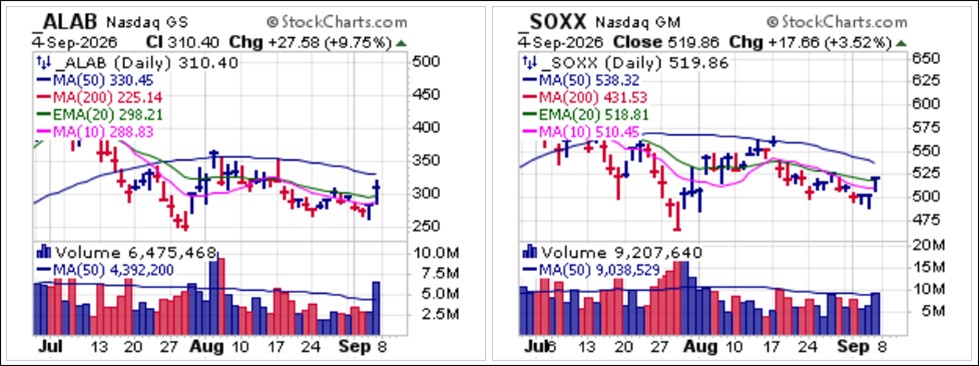
 We also reported on pocket pivots in Astera Labs (ALAB) and the iShares Semiconductor (SOXX) ETF. These both differ from MU and SNDK in that these pocket pivots occurred at the lower 10-dma and 20-dema as both ALAB and SOXX remain below 50-dma resistance.
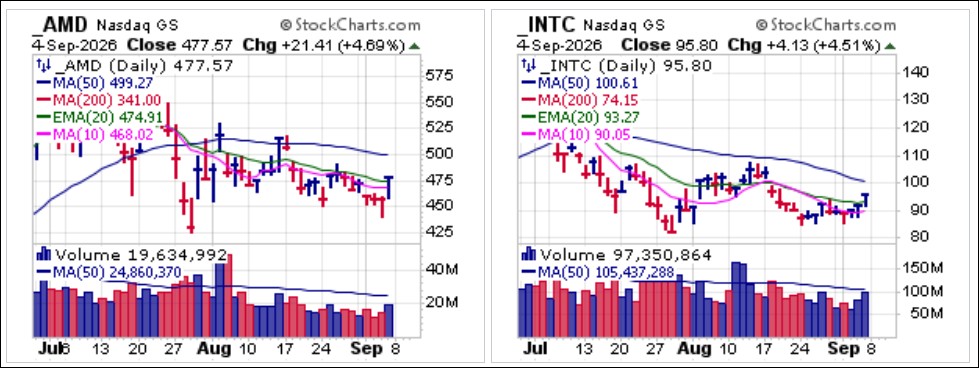
 These were similar to the pocket pivots seen in Advanced Micro Devices (AMD) and Intel (INTC) on Friday which also occurred at 10-dma/20-dema resistance as the stocks remain below 50-dma resistance.
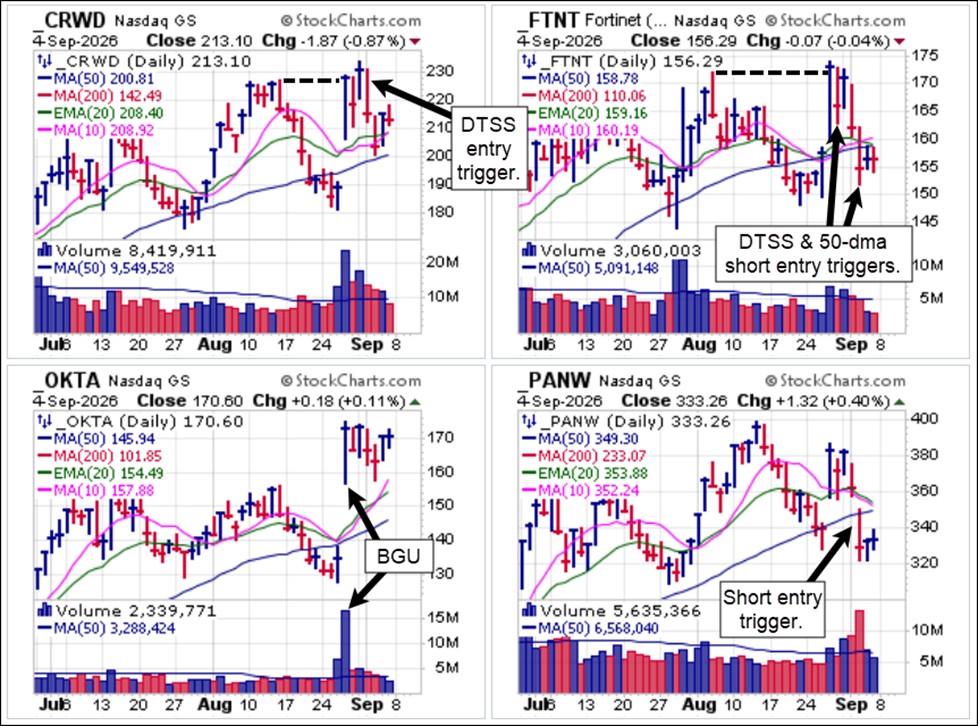
 Displays of strength in this market, however, have met with mixed results. Cybersecurity names, which were breaking out last week and early this past week have steadily deteriorated. CrowdStrike (CRWD) and Fortinet (FTNT) both posted double-top short-sale entries this past Monday and two Fridays ago, respectively. FTNT also triggered a short entry as it broke 50-dma support on Wednesday. Palo Alto Networks (PANW) gapped down through its 50-dma on Wednesday after reporting earnings Tuesday afternoon to trigger a short-sale entry at that point. Okta (OKTA) remains the one standout as it continues to form a bull flag following a buyable gap-up (BGU) move after earnings the prior week.
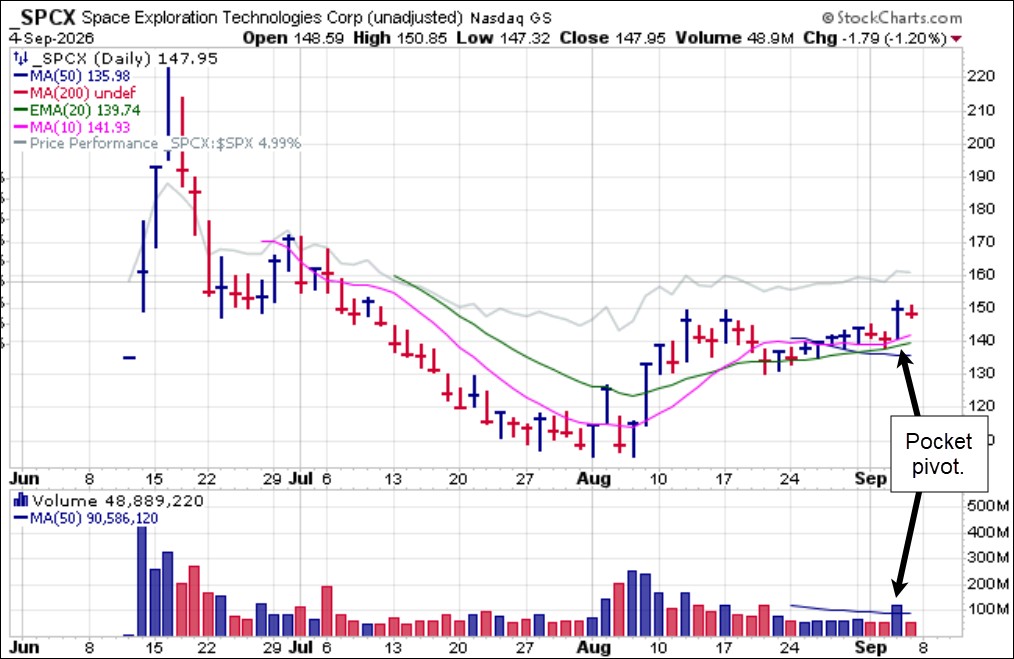
 We also reported the pocket pivot in SpaceX (SPCX) on Thursday. The stock then pulled back slightly on Friday and we would look for entries as close to the 10-dma as possible on any further pullbacks from here.
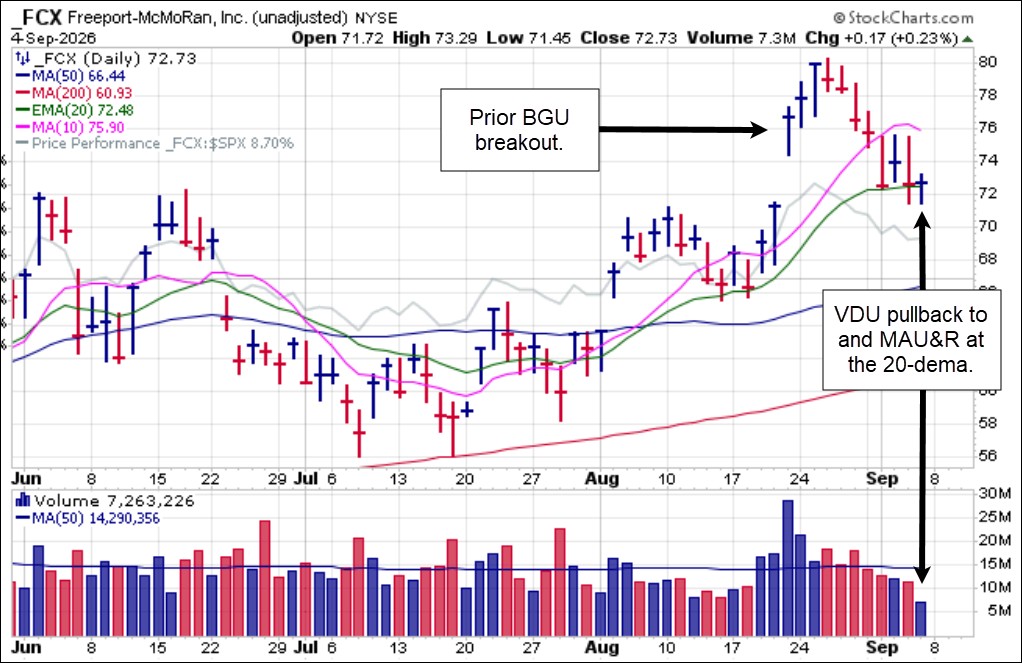
 Copper prices remain near all-time highs with Copper Futures ending the week at $6.68. Copper miners like Freeport-McMoRan (FCX) which broke out two weeks ago on BGU moves to new highs have failed on those BGUs. However, recent pullbacks to the 20-dema have in some cases presented potentially opportunistic long entries. FCX posted a VDU pullback to the 20-dema on Friday, in addition to an MAU&R at the line. This presents a potential long entry using Friday's low or the 20-dema as a tight selling guide.
 In general, the market appears to be biding its time and investors shuffle in and out of various stock groups. We might surmise that the market is waiting on the Fed on September 16th when they release their next policy statement. CME FedWatch currently assigns a 58.6% probability of a 1/4-point rate hike, only slightly better than a coin flip. Of more immediate importance will be this Thursday's Producer Price Index and Friday's Consumer Price Index reports. Headline PPI is expected come in a little hotter at 0.4% while core PPI is expected to print lower at 0.2%. Headline CPI is also expected to be somewhat elevated at 0.4% while core PPI is expected to come in at a relatively 0.1%. Surprises in either direction will likely impact the market's assessment of what the Fed will do on September 16th.
The Market Direction Model (MDM) remains on a BUY signal.